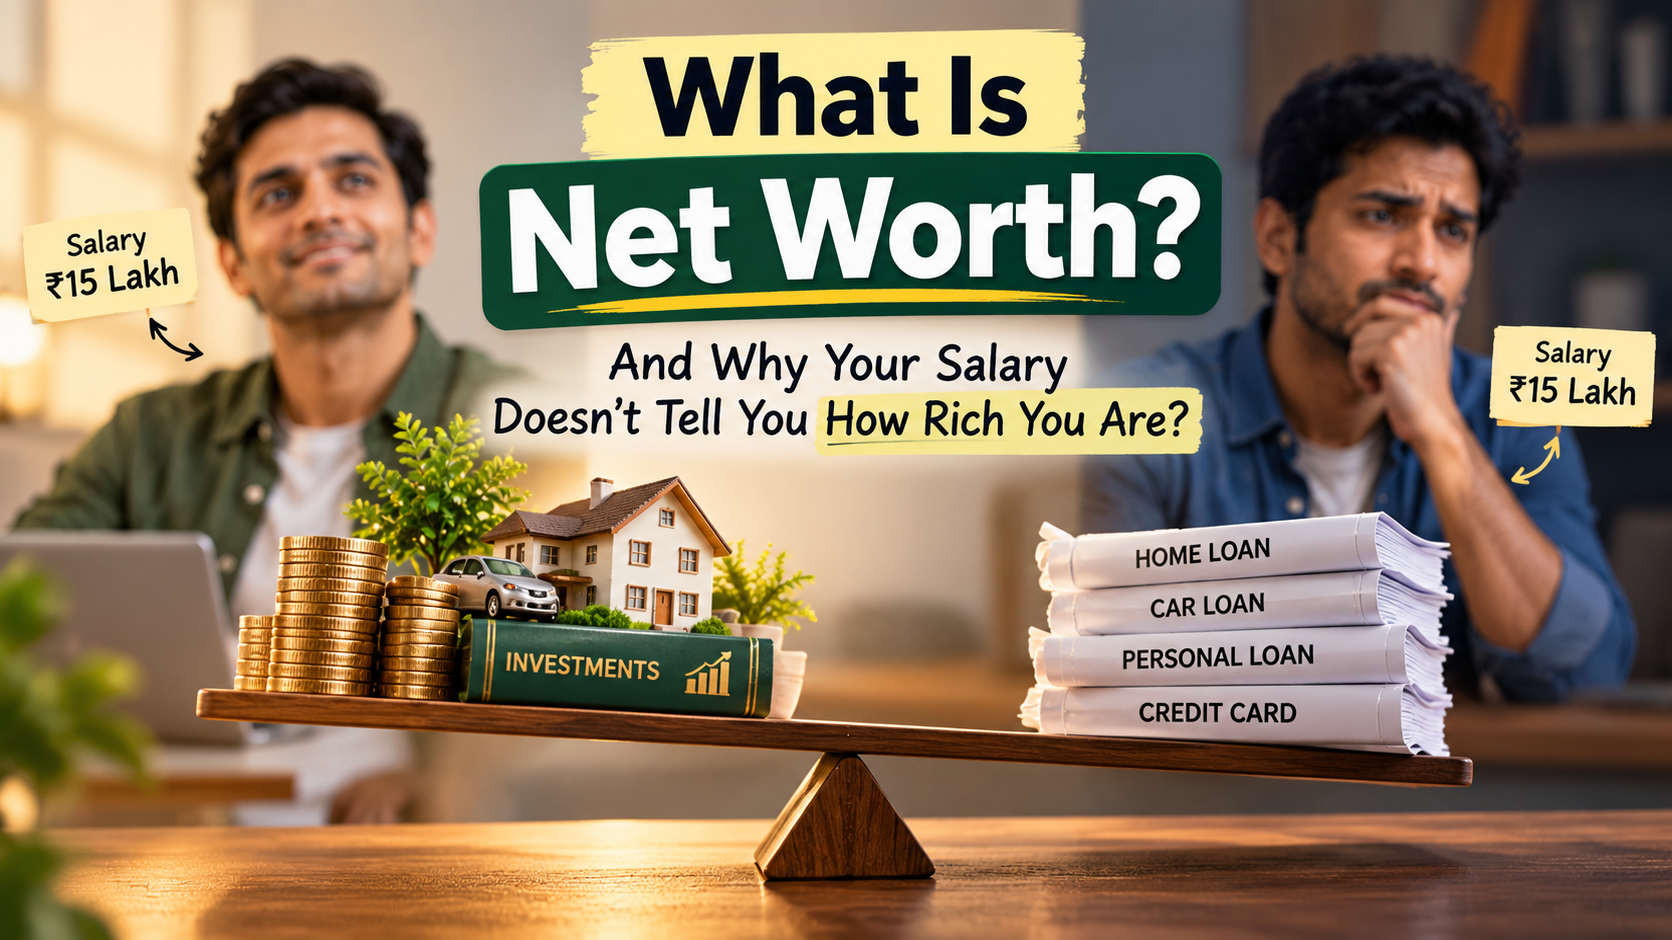
What Is Net Worth - And Why Your Salary Doesn't Tell You How Rich You Are?
Imagine two people, Rahul and Amit.
Both are 30 years old and both earn ₹15 lakh a year.
Rahul has ₹8 lakh in savings and investments, owns a car worth ₹6 lakh, and has no loans.
Amit has ₹12 lakh in investments, but also has a ₹7 lakh personal loan and ₹25 lakh outstanding on a home loan.
Who is richer?
Looking only at their salaries won't tell you.
The answer becomes much clearer when we look at their net worth.
What is net worth?
Net worth is simply:
Net Worth = What you own - What you owe
What you own is called your assets.
What you owe is called your liabilities.
For example, suppose you have:
- ₹5 lakh in bank accounts and fixed deposits
- ₹7 lakh in mutual funds and stocks
- A car worth ₹6 lakh
- Gold worth ₹2 lakh
Your total assets are:
₹5L + ₹7L + ₹6L + ₹2L = ₹20 lakh
Now suppose you also have:
- ₹3 lakh remaining on a personal loan
- ₹10 lakh outstanding on a home loan
Your total liabilities are ₹13 lakh.
Therefore:
Net worth = ₹20 lakh − ₹13 lakh = ₹7 lakh
So although you own ₹20 lakh worth of assets, your actual net worth is ₹7 lakh.
Why salary doesn't tell you how wealthy you are
Salary tells you about income.
Net worth tells you about your financial position.
Someone earning ₹30 lakh a year could have a very low net worth if they spend almost everything they earn and have large debts.
Meanwhile, someone earning ₹12 lakh could potentially build a substantial net worth by consistently saving, investing, and keeping debt under control.
That's why a high salary and high net worth are not the same thing.
Think of it this way:
Income is the fuel coming into your financial system.
Net worth is what you've accumulated after accounting for what you owe.
A simple example
Suppose Priya earns ₹1 lakh per month.
After all her expenses, she invests ₹25,000 every month.
She also has a ₹20 lakh home loan.
Her colleague earns the same ₹1 lakh but spends ₹95,000 every month and has ₹5 lakh of credit-card and personal-loan debt.
Their salaries are identical.
Their financial positions aren't.
Over time, the difference can become significant because Priya is building assets while gradually reducing her liabilities.
But there's an important catch
Net worth isn't the same as having cash in your bank account.
Suppose you own a house worth ₹80 lakh but have ₹60 lakh remaining on the home loan.
The house contributes to your assets, while the outstanding loan is a liability.
So the house contributes roughly ₹20 lakh to your net worth, before considering transaction costs and other factors.
This is why simply saying:
"I own an ₹80 lakh house, so I'm worth ₹80 lakh."
would be incorrect.
You have to look at what you owe against what you own.
Assets aren't all equally useful
Another important distinction is what kind of assets you own.
₹10 lakh sitting in a bank account, ₹10 lakh invested in a diversified portfolio, and ₹10 lakh locked inside an illiquid asset may all appear as ₹10 lakh of assets on paper.
But they don't have the same liquidity, risk, return potential, or accessibility.
So net worth is an important starting point—not the entire picture of your financial health.
How should you calculate your net worth?
You can do this once or twice a year.
Make two lists.
Assets
- Bank balances
- Fixed deposits
- Mutual funds
- Stocks
- EPF and other retirement investments
- Gold
- Property
- Other meaningful assets
Then list your liabilities:
- Home loan
- Car loan
- Personal loan
- Education loan
- Credit-card outstanding
- Other debt
Then calculate:
Net Worth = Total Assets − Total Liabilities
That's your current financial snapshot.
And the number itself isn't the most important thing.
What's more useful is watching how it changes over time.
If your income increases but your net worth barely moves, you may be spending most of the additional income.
If your income stays relatively stable while your net worth steadily increases, your financial system may be working well.
The takeaway
Don't use your salary as the only measure of financial progress.
Track three things:
How much you earn.
How much you owe.
How much you own.
Your salary tells you what comes in.
Your expenses determine what stays.
And your assets minus liabilities tell you what you've actually built.
That's net worth.
This article is for educational purposes only and should not be considered personalised financial advice.